Key Takeaways
- Maintaining a conservative portfolio that preserves capital typically takes priority over wealth preservation around five to ten years before retirement.
- Over time, accumulating wealth becomes riskier because high-value portfolios are more susceptible to major losses.
- As you approach your golden years, your portfolio has less time to recover from bear markets, your risk tolerance is lower, and managing volatile assets becomes more stressful.
- Gold is the ideal financial instrument for preserving capital. For centuries, it has remained a dependable store of value and a safe-haven hedge against economic downturns.
- Silver is another excellent option, offering similar benefits to gold, but with high upside potential due to its high industrial demand.
Capital preservation is a strategy for protecting the value of the nest egg you’ve built over the years. While there’s never a wrong time to invest conservatively, it’s common to focus especially heavily on wealth preservation over accumulation within five to ten years of retirement.
In our younger years, chasing aggressive gains makes sense. Your risk tolerance is naturally higher, as you have plenty of time to recover if your portfolio takes a hit. As we approach our golden years, high-stakes investments don’t have the same appeal due to the inherent risk.
In this guide, we’re going to explain why and when to consider switching from offense to defense. We’ll also highlight the benefits of a capital preservation portfolio and explain how to build your defensive buffer. Let’s jump right in.
Why Investment Priorities Change Over Time
Different stages of life call for different investment strategies. Your goals and priorities in life shift, so your portfolio should adapt accordingly.
Although you should still focus on long-term financial goals at a young age, it’s common to allocate at least a small portion of capital to growth-prone assets, like small-cap stocks, tech funds, emerging market equities, and even cryptocurrencies if you have a high risk tolerance.
Closer to retirement, adopting a capital preservation strategy isn’t only standard practice because it provides peace of mind. There are logical reasons to shift gears.
Mitigating Significant Swings
As your nest egg grows larger, even minor swings can have a major impact. For example, let’s say your $10,000 portfolio drops by 20%. You lose $2,000. It’s not ideal, but it’s not the end of the world. Now, let’s say your $1,000,000 portfolio drops by 20%. That’s a $200,000 loss.
One could make the argument that you’re losing 20% either way, but losing $200,000 is naturally more daunting, regardless of your overall net worth. A capital preservation portfolio prevents significant movements in either direction.
It’s not just mental turmoil you need to worry about. Recovering $2,000 is pretty easy, especially when you’re young and have plenty of time. Recovering $200,000 will require another high-risk decision that isn’t guaranteed to work out. If you’re not careful, one loss can lead to another.
Chasing losses can quickly switch from investing to gambling. All it takes is a few wrong moves to wipe out a lifetime of hard-earned savings. The risk just isn’t worth the reward.
Buffer Against Long-Term Bear Markets
Economic uncertainty is just that: uncertain. What happens if a period of stagflation lasts for a decade or longer? If you adopted a capital preservation strategy beforehand, your nest egg should be able to weather the storm. If not, your portfolio would bleed purchasing power.
As we get older, every investment year counts. One bad year can move the needle significantly, and multiple bad years in a row, with no time to recover, can be devastating.
Sequence of Returns Risk
Sequence of returns risk is the danger that your portfolio could start performing poorly once you start withdrawing money for living expenses.
If your volatile assets plummet at an inopportune time, you’re forced to sell at depressed prices, significantly and permanently diminishing your savings.
A well-diversified capital preservation portfolio is more likely to retain its value during economic turbulence. Even if traditional markets falter, your nest egg should still be able to withstand the stormy economic weather without being depleted early.
Maintaining a Stable Lifestyle
Evolving your investment strategy over time also makes sense because your career moves in stages until eventually ending at retirement.
When you have a steady paycheck coming in, you can be more frivolous with your spending because you know more capital is on the way. When you’re close to retirement, stable investments replace a stable paycheck.
Adopting a capital preservation strategy is just a fancy way to say “save for a rainy day.” You’re tightening up your spending and preparing for the next chapter.
Practical Living Expenses
Changing investment priorities near retirement is a prudent move purely from a risk-reward viewpoint. In retirement, losing half of your portfolio can drastically affect your quality of life. Financial loss can ruin plans and make it difficult to enjoy your golden years to the fullest.
Leaving a Legacy
Focusing on financial security isn’t only about catering to your own needs. If you wish to hand down generational wealth to your loved ones, you must be diligent and cautious. Maintaining a capital preservation portfolio today lets you leave a lasting, tangible legacy tomorrow.
Gold Is a Reliable Store of Long-Term Value
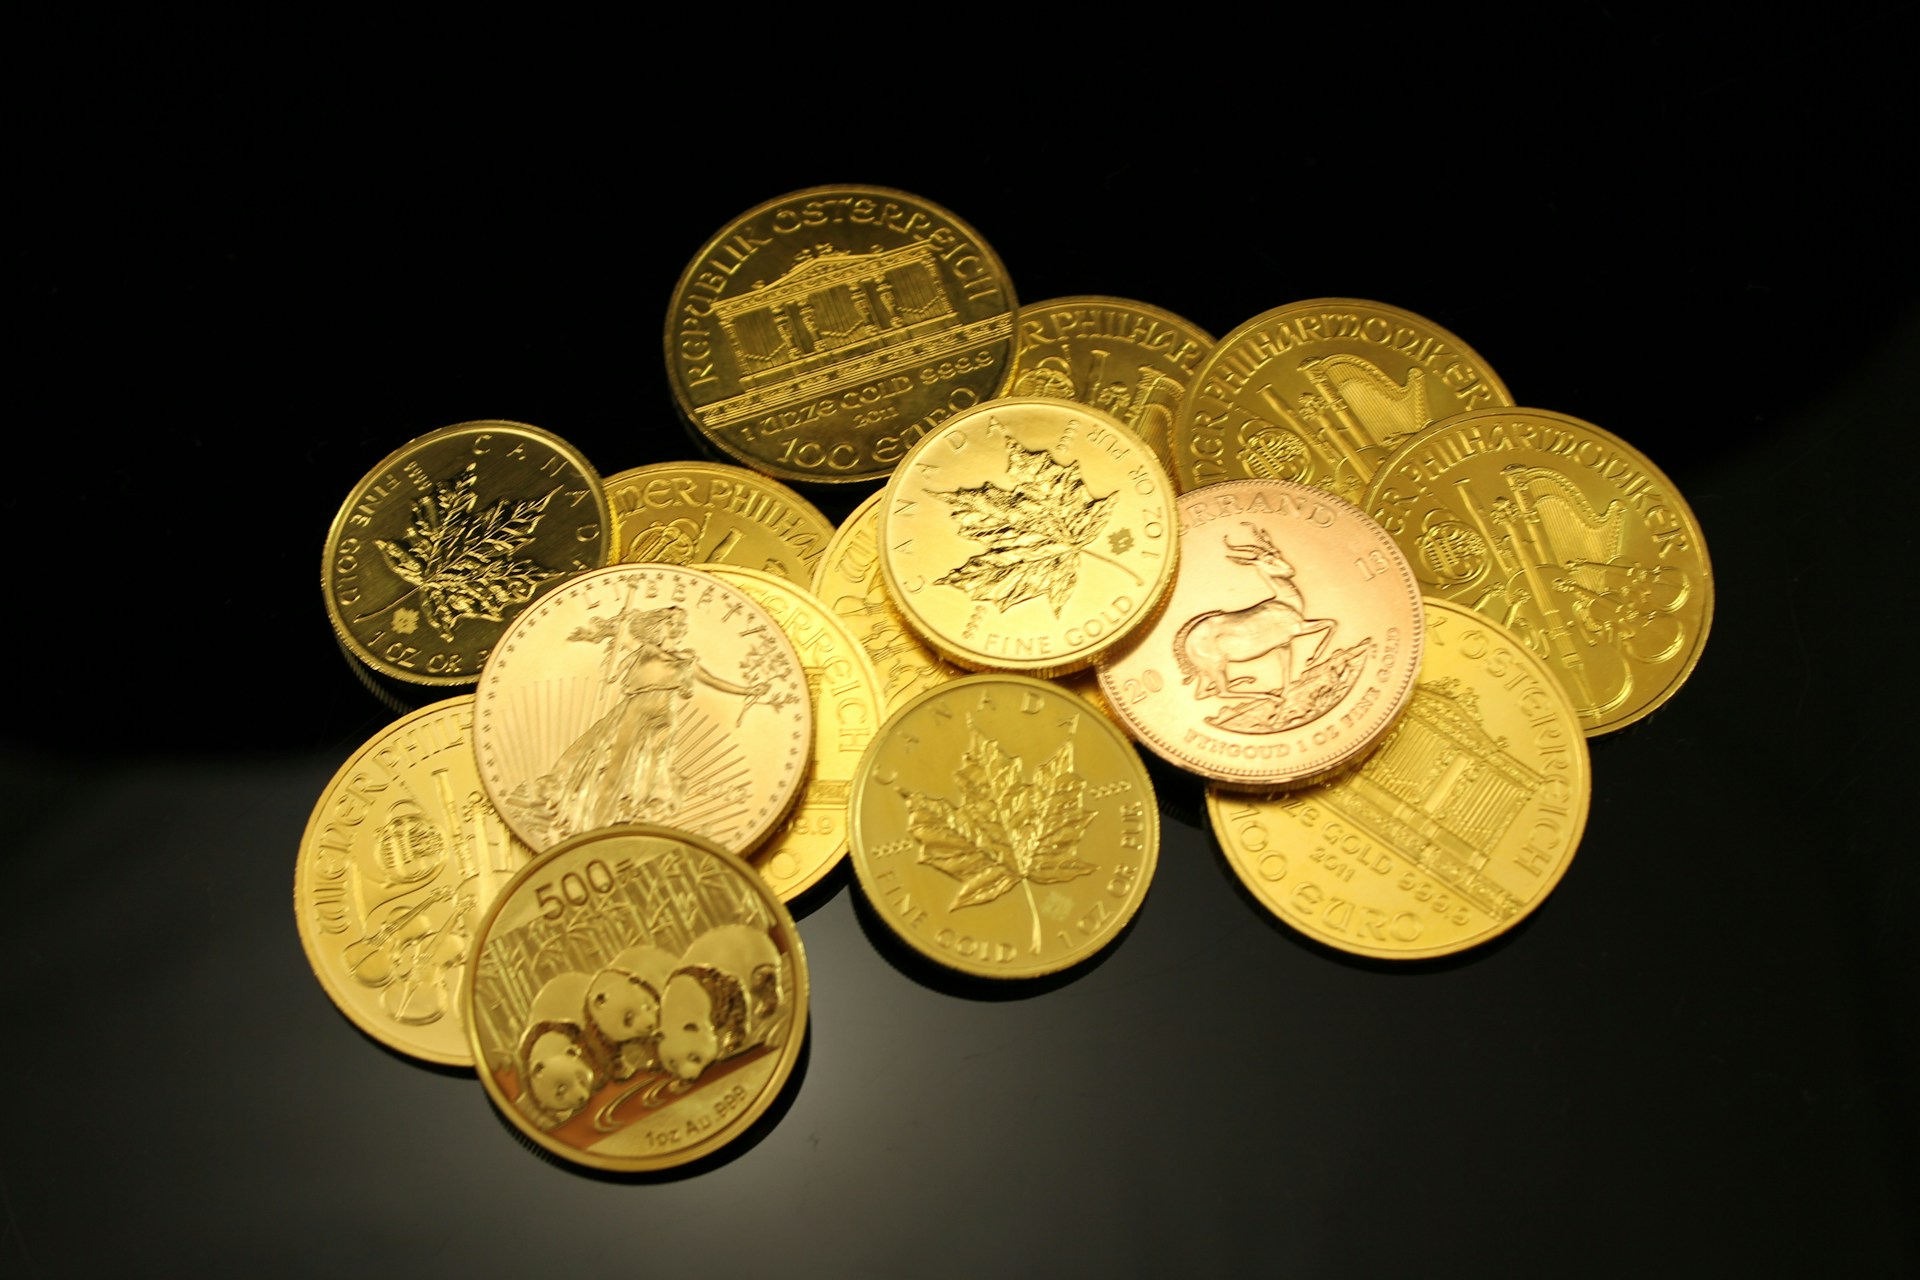
For thousands upon thousands of years, humans have put their trust in gold as a way to preserve and protect wealth. The precious yellow metal has become deeply ingrained in cultures around the world, serving as a universally recognized store of value.
Few would argue that gold possesses all of the attributes of a currency: scarcity, durability, divisibility, fungibility, recognizability, and portability. It’s also a hard alternative asset that performs very differently compared to traditional investments.
What makes gold the ideal financial instrument for building a defensive capital preservation strategy?
A Time-Tested Hedge Against Inflation
As the costs of goods and services rise during periods of inflation, and fiat fails to keep pace, gold historically retains its purchasing power. And because in-the-know investors tend to buy gold during tumultuous economic conditions, its spot price often rises when other markets fall.
Tangibility and Intrinsic Value
Gold is a rare, finite resource that cannot be created. It’s also a tangible asset with true, intrinsic value. Paper money, on the other hand, can be printed and destroyed at will.
Industrial and Institutional Demand
Adding gold to a capital preservation portfolio makes sense from a basic supply and demand perspective. Gold’s unique properties make it crucial in high-end electronics and medical technologies, alongside massive institutional demand from global central banks.
No Counterparty Risk
Traditional assets are directly tied to countless factors that can affect their worth. For example, a CEO’s bad decision can cause the company’s stock to plummet. Precious metals are unbound by third parties.
Global Recognition
Precious metals are highly liquid assets that are recognized and traded worldwide. Converting your gold to capital is a frictionless process, especially with our buyback guarantee.
Proven History
A rock-solid capital preservation strategy should be based on concrete facts. One can simply look at gold’s past performance to gain trust in its future. Of course, we can’t predict anything with certainty, but gold has proven its resilience over the course of centuries.
Diversification
A well-diversified portfolio is able to withstand market volatility. Even if one asset plummets, the portfolio’s overall value remains relatively unscathed. The vast majority of experts recommend allocating at least a small portion (typically 5% to 15%) of a retirement portfolio to gold.
Silver Is a High-Upside Option
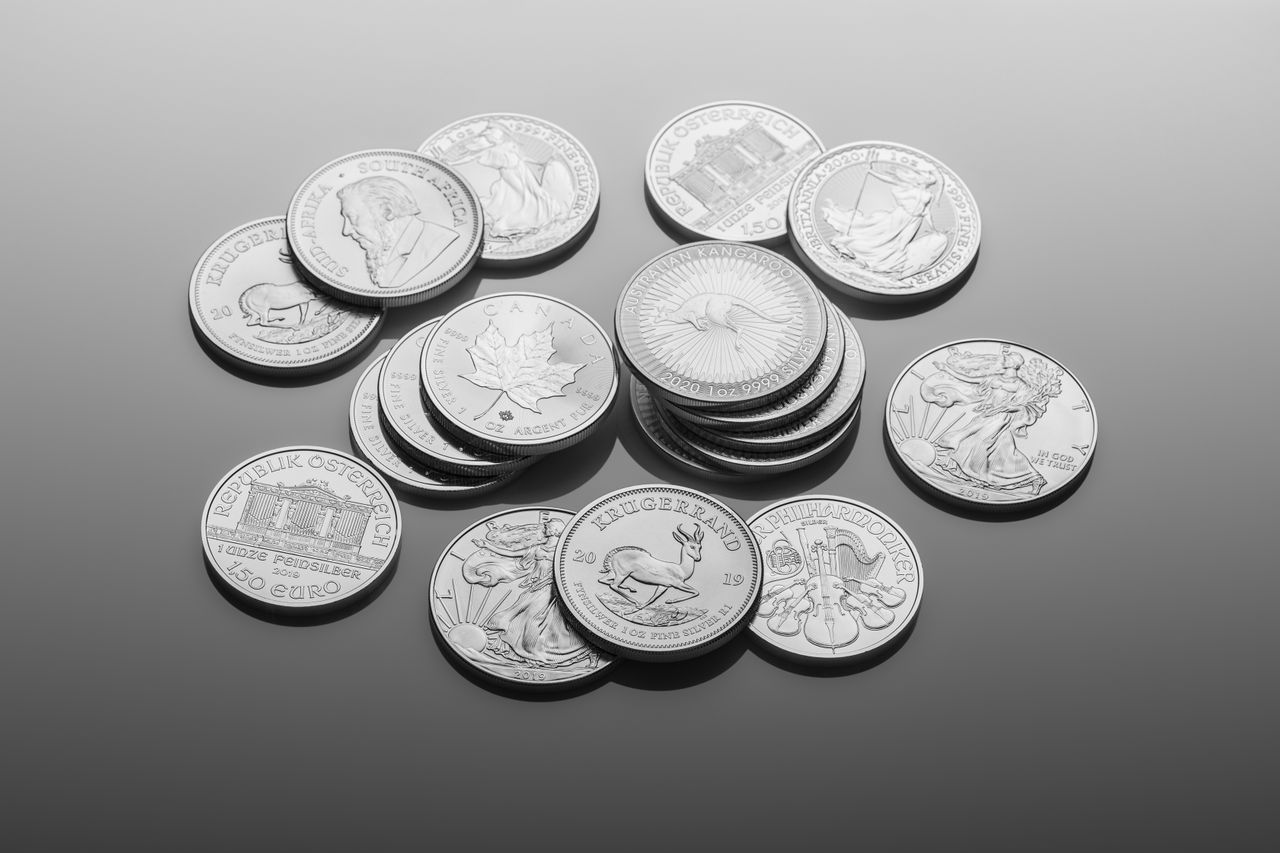
Investing in gold is the quintessential approach to creating a capital preservation portfolio, but silver is a compelling option, too.
Silver offers many of the same benefits as gold, but many investors speculate that it will grow significantly in value in the future due to its smaller market, rapidly diminishing supply, and growing market demand.
While silver is stable compared to other assets, it’s more volatile than gold. Some investors enjoy the higher upside potential, but it’s worth noting that there’s slightly more risk, too.
Call for a Free Consultation
It’s never too early to start preparing for your golden years. If you need personalized assistance developing a capital preservation strategy, contact us at 800-605-5597 for a free consultation. A qualified precious metals specialist can help you make an informed decision.
In addition to selling government-backed gold coins for private ownership, we can help you set up a precious metals retirement account or execute a gold IRA rollover. You can expect concierge-level service every step of the way. Protect and preserve your nest egg with gold.
About the Author